Table of Contents
If you have ever needed quick cash and wondered whether taking a cash advance would damage your credit score, you are not alone. The relationship between cash advances and credit scores is one of the most misunderstood topics in personal finance, and the answer is more nuanced than a simple yes or no. Whether a cash advance hurts your credit depends entirely on the type of advance you take, which product you use, and how you manage the repayment process.
This guide breaks down every scenario clearly, so you understand exactly what happens to your credit score when you take a cash advance, which options protect your score, and why platforms like Beem offer a genuinely credit-safe alternative for users who need fast access to funds without the risk of credit damage.
What Is a Cash Advance and How Does It Affect Credit?
A cash advance is a short-term borrowing product that provides immediate access to cash outside of a standard purchase or loan transaction. The term covers several different products, and the credit impact varies significantly depending on which type you use.
The three most common types of cash advances are credit card cash advances, payday loans, and app-based cash advances. Each one interacts with your credit profile in a completely different way. Understanding which type you are dealing with before you apply is the single most important step you can take to protect your credit score during a short-term financial crunch.
Credit Card Cash Advances and Your Credit Score
A credit card cash advance allows you to withdraw cash using your credit card, either from an ATM or through a convenience check issued by your card provider. This type of advance is the most common source of credit score concern, and for good reason.
Credit card cash advances affect your credit score in several ways. First, the cash advance draws against your available credit limit. This increases your credit utilization ratio, which is the percentage of your total available credit that you are currently using. Credit utilization is one of the most heavily weighted factors in your credit score calculation, accounting for approximately 30 percent of your FICO score. If the cash advance pushes your utilization above 30 percent of your available credit, your score is likely to drop noticeably until the balance is paid down.
Second, some credit card issuers treat cash advances as a separate balance category with a higher interest rate and no grace period. Interest begins accruing from the day of the transaction rather than the end of the billing cycle. This means even a small delay in repayment results in a growing balance that further inflates your utilization ratio over time.
Third, if the increased balance leads to missed or late payments, those payment history marks have the most significant negative impact of all, accounting for approximately 35 percent of your FICO score.
Do Payday Loans Hurt Your Credit Score?
Payday loans occupy an interesting position in the credit scoring landscape. Most traditional payday lenders do not report positive repayment history to the major credit bureaus, which means paying off a payday loan on time does nothing to build your credit. However, if a payday loan account goes to collections due to non-payment, that collection account is typically reported to the credit bureaus and can severely damage your credit score.
The application process for payday loans may also trigger a hard inquiry depending on the lender. Some payday lenders perform a hard credit pull as part of their approval process, which can reduce your score by a small amount temporarily. Others use alternative data or soft inquiries that do not affect your score. This varies by lender, so it is always worth confirming before applying.
Hard Inquiries vs Soft Inquiries on Credit Reports
Understanding the difference between hard and soft credit inquiries is essential for anyone managing their credit score while seeking short-term cash.
A hard inquiry occurs when a lender or financial institution pulls your full credit report to make a lending decision. Hard inquiries are recorded on your credit report and can lower your score by a few points each time they occur. Multiple hard inquiries within a short period are interpreted by scoring models as a sign of financial stress, which compounds the negative impact. Hard inquiries remain on your credit report for two years, though their scoring impact typically fades after about 12 months.
A soft inquiry occurs when you check your own credit, when a lender performs a pre-qualification check, or when a financial platform reviews your account activity without initiating a formal credit decision. Soft inquiries do not appear on your credit report to lenders and have no impact on your credit score whatsoever.
Read: Beem For Avoiding Payday Loans
Do App-Based Cash Advances Hurt Your Credit Score?
App-based cash advances, the type offered through fintech platforms rather than banks or payday storefronts, generally have the most favorable credit impact of all three categories. Most modern cash advance apps do not perform hard credit inquiries as part of their approval process, which means using them does not directly lower your credit score.
Instead of pulling a traditional credit report, these platforms evaluate eligibility using alternative data such as account activity, income patterns, and deposit history. This approach is more reflective of a user’s current financial situation and eliminates the credit score risk that comes with hard inquiry-based approval processes.
However, not all app-based cash advances are created equal. A small number of platforms do perform credit checks or report to credit bureaus under certain conditions. Always confirm the credit policy of any platform before submitting a request.
How Beem Cash Advances Protect Your Credit Score
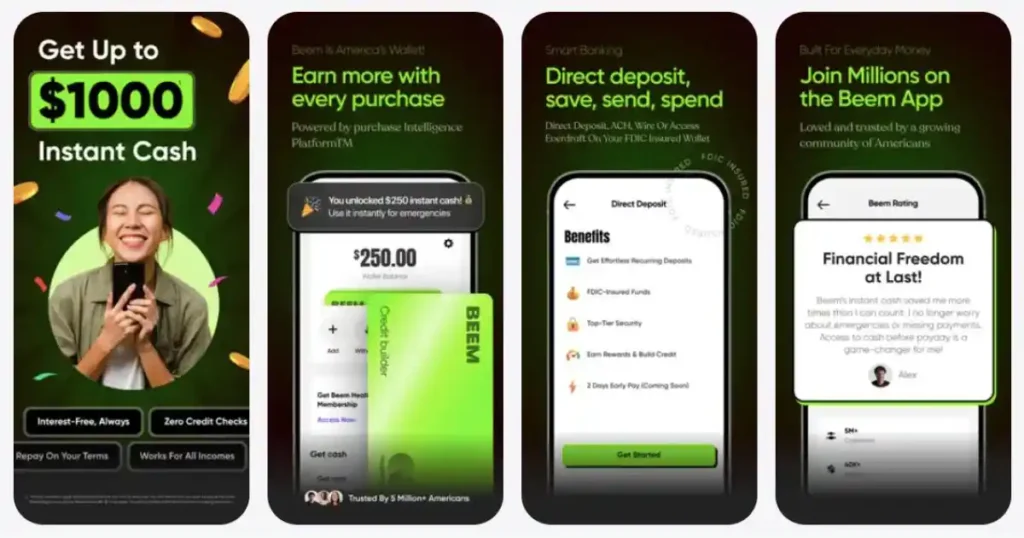
Beem is one of the clearest examples of a cash advance platform built with credit score protection as a core design principle. The Beem cash advance requires no hard credit inquiry at any point in the process. Approval is based entirely on real-time account activity and income patterns rather than a static credit score or formal credit report pull.
This means using Beem does not lower your credit score, does not add an inquiry to your credit report, and does not create any negative mark visible to other lenders. For users who are actively building or repairing their credit, this distinction is critically important. Taking a cash advance through Beem to cover a short-term gap does not create a new credit problem on top of the financial situation you are already managing.
Beem offers eligible users instant cash advances from $10 to $1,000 with no interest, no credit check, and repayment tied to your verified deposit cycle. Because there is no interest accruing on the advance, there is no risk of a growing balance pushing up your utilization ratio the way a credit card cash advance does. You borrow what you need and repay exactly that amount.
Credit Utilization and Cash Advances: What You Need to Know
Credit utilization is the factor most directly affected by credit card-based cash advances. Keeping your credit utilization below 30 percent is the standard recommendation from credit professionals, with lower utilization generally associated with higher scores.
When you take a credit card cash advance, the amount drawn is immediately reflected in your outstanding balance. If your card has a $3,000 limit and you take a $1,000 cash advance, your utilization on that card jumps from zero to 33 percent with a single transaction, potentially pushing your score below the threshold that many lenders use as a benchmark for creditworthiness.
How Long Cash Advance Impact Lasts on Your Credit
The credit impact of a cash advance is not permanent in most cases, but the timeline for recovery depends on how quickly the balance is repaid and whether any payments are missed along the way.
For credit card cash advances, the utilization impact disappears as soon as the balance is paid down. If you repay the advance within the same billing cycle and your card reports a low balance to the bureaus, the score impact may be minimal or temporary. However, because credit card cash advances carry high interest from day one, carrying the balance for multiple billing periods adds cost while sustaining the utilization impact.
Hard inquiry marks from loan applications fade in impact after approximately 12 months and are removed from your report entirely after 24 months. Late or missed payment marks, the most damaging type of credit score event, remain on your report for up to seven years.
Cash Advance Alternatives That Do Not Hurt Your Credit
For users who need fast access to cash but want to avoid credit score impact entirely, the clearest solution is choosing a platform that uses no hard inquiry, no credit reporting, and no interest-accruing balance structure.
Best No Credit Check Cash Advance Options
No credit check cash advance apps are designed specifically to bypass the traditional credit evaluation process. They approve users based on banking activity and income rather than credit history, which means the entire transaction happens outside of the credit reporting ecosystem when managed responsibly.
Beem is among the strongest options in this category. The platform combines no credit check approval with no interest charges, multiple payout options, and a repayment structure tied to your actual income timing rather than an arbitrary external deadline. For users who are already managing credit challenges, this approach removes the risk of compounding those challenges with a new inquiry or a new debt balance reported to the bureaus.
Other app-based platforms in this category include earned wage access tools that let you draw against already-earned income without a credit check. These products also avoid credit bureau reporting for standard transactions, though the advance limits are often tied strictly to verified employer payroll data, which excludes gig workers and freelancers with non-traditional income.
Cash Advances and Credit Score: The Specific Scenarios Explained
To make this completely clear, here is a direct breakdown of how each type of cash advance interacts with your credit score.
A credit card cash advance raises your credit utilization immediately, begins accruing interest from day one, and can trigger late payment marks if the balance grows beyond what you can repay. This type carries the highest credit score risk of all cash advance options.
A payday loan typically does not report to credit bureaus for on-time payments but can severely damage your score if it goes to collections. Some lenders perform a hard inquiry during application. This type carries moderate credit score risk depending on the lender’s policies.
A no credit check app-based cash advance from a platform like Beem performs no hard inquiry, reports no balance to credit bureaus, and charges no interest that could cause a growing balance. This type carries the lowest credit score risk of all available cash advance options.
When a Cash Advance Can Indirectly Affect Your Credit
Even a no credit check cash advance can indirectly affect your credit if it is used to fund a pattern of spending that eventually leads to missed payments on other accounts. If taking a cash advance prevents you from covering a credit card minimum payment or a loan installment, the resulting late payment mark on those accounts is a credit event tied to the advance, even if the advance itself did not touch your credit report.
This is why responsible cash advance use is always tied to a clear repayment plan and a specific short-term purpose. Using a small advance to bridge a timing gap, avoid an overdraft fee, or cover a bill due before payday is a legitimate and financially sound use case. Using advances repeatedly to fund ongoing spending beyond your income creates a cycle that eventually affects your broader financial health, including your credit.
How to Use Cash Advances Without Damaging Your Credit Score
The practical rules for protecting your credit when using cash advances are consistent across all the scenarios covered in this guide.
Avoid credit card cash advances unless absolutely necessary and you can repay the balance within the same billing cycle. The combination of high interest, no grace period, and immediate utilization impact makes this the most credit-damaging cash advance option by a significant margin.
Choose a no credit check platform like Beem for app-based cash advances to avoid hard inquiries and keep the transaction outside of the credit reporting system entirely. Borrow only what you need for the specific expense you are covering and repay on the schedule confirmed before you requested the advance.
Monitor your credit score regularly using free monitoring tools so you can identify and address any unexpected changes quickly. Several banks and credit card providers now offer free credit score monitoring through their apps, and platforms like Beem provide financial tools that support broader financial awareness alongside the cash advance feature.
Check out Beem for on-point financial insights and recommendations to spend, save, plan and protect your money like an expert. Download the Beem app today!
Frequently Asked Questions
Do cash advances hurt your credit score?
It depends on the type. Credit card cash advances can hurt your credit by raising your utilization ratio and accruing interest on a growing balance. Payday loans carry moderate risk. App-based cash advances from platforms like Beem use no hard credit inquiry and report no balance to the bureaus, making them the safest option for your credit score.
Does a cash advance app like Beem affect my credit score?
No. Beem does not perform a hard credit inquiry and does not report cash advance balances to credit bureaus. Approval is based on real-time banking activity and income patterns rather than a credit report. Your credit score is not impacted at any point during the Beem cash advance process.
How much does a credit card cash advance lower your credit score?
The impact varies based on your current utilization and total available credit. A cash advance that pushes your utilization above 30 percent of your available credit can reduce your score noticeably. The impact is reversed as the balance is paid down, but high interest charges can cause the balance to grow if repayment is delayed.
Can I get a cash advance with bad credit?
Yes. No credit check cash advance platforms like Beem approve users based on banking activity and income rather than credit scores. Users with bad credit, thin credit files, or limited credit history can qualify for a Beem cash advance without any credit score impact. Visit trybeem.com/get-instant-cash-advance to check your eligibility today.
What is the safest type of cash advance for your credit score?
App-based cash advances from no credit check platforms are the safest for your credit score. Beem offers advances from $10 to $1,000 with no hard inquiry, no credit bureau reporting, no interest charges, and repayment tied to your verified deposit cycle, making it the most credit-safe short-term cash option available for most users.