
Table of Contents
Living on a fixed income is hard. Disability benefits arrive once a month, but rent, groceries, medication, utilities, and medical transport do not wait for payday. When a surprise expense lands in the middle of the month, many people on SSI or SSDI need a quick, low-cost way to bridge the gap.
That is where cash advance apps for disability recipients come in. The right app can give you early access to your own money without a credit check or a predatory interest rate. The wrong one can trap you in fees, tips, and repeat borrowing.
This guide explains how these apps work for people on disability benefits, which ones are worth a look in 2026, what to check before you sign up, and what other options exist if an app is not the right fit.
What Are Cash Advance Apps for Disability?
A cash advance app lets you access a small amount of money before your next deposit arrives. Instead of applying for a traditional loan, you link your bank account, the app reviews your deposit history and account activity, and it offers an advance based on what it sees.
For people receiving disability benefits, the appeal is simple. Government payments are predictable, and many apps can recognize recurring deposits from the Social Security Administration (SSA) as steady income.
How They Differ From Payday Loans
Cash advance apps and payday loans are often lumped together, but they are not the same thing.
- Payday loans usually carry very high APRs, short repayment windows, and can lead to a cycle of rollovers.
- Cash advance apps typically offer smaller amounts, often with no interest, and repay automatically from your next deposit.
- Personal loans offer larger amounts and longer terms, but usually involve a credit check and a fixed interest rate.
Each has a place. For a small gap of $50 to a few hundred dollars, an app is often the cheaper and simpler route, as long as you understand the fee structure.
Why Disability Recipients Face Unique Cash Flow Challenges
Several factors make budgeting on benefits especially tight:
- Fixed payment dates: SSI generally pays on the first of the month, while SSDI is paid on a schedule tied to your birth date. If a bill is due before your deposit, there is no flexibility.
- Higher living costs: Medical equipment, prescriptions, specialized transport, and in-home support can add up quickly.
- Limited access to credit: Many people on benefits have thin or damaged credit files, which makes traditional borrowing harder.
- Strict resource limits for SSI: Because SSI is means-tested, borrowing and saving decisions deserve extra care (more on that below).
Can You Use a Cash Advance App on SSI or SSDI?
In most cases, yes. Many cash advance apps look at the pattern of deposits in your bank account rather than the source of the income. If your SSI or SSDI payment lands in your account on a regular schedule, an app can often treat it as qualifying income.
That said, eligibility rules differ by app, and none of them guarantee approval.
What Apps Usually Look For
Most apps review a handful of common signals:
- A checking account that is at least a few weeks or months old
- Regular, recurring direct deposits
- A positive or stable account balance history
- A linked debit card for receiving funds
- Account activity that suggests you can repay on your next deposit date
Does a Cash Advance Count as Income for SSI?
This is the question people ask most, and it deserves a careful answer. In general, money you must pay back is treated differently from income. But the rules around SSI are detailed, and individual situations vary. If you receive SSI, it is worth confirming with the SSA or a benefits counselor before you rely on any form of borrowing, especially if you borrow often or hold a balance in your account over the resource limit.
This article is informational only and is not legal or financial advice. When in doubt, ask a professional who understands your benefits.
What to Look for in a Cash Advance App for Disability
Not every app treats fixed-income users equally. Before you download anything, run through this checklist.
1. Transparent Fees
Some apps charge a monthly membership. Others charge an express fee for instant transfers. Some ask for “optional” tips that can function like hidden interest. Add up every possible cost, then compare it to the amount you are borrowing.
A useful rule: if a $50 advance costs you $8 in fees to receive on time, you are effectively paying a very high rate for a very short loan.
2. No Credit Check Requirement
Many apps do not run a hard credit pull. This matters if you have limited credit history or are rebuilding. Confirm the app does not report a missed repayment in a way that could hurt you.
3. Repayment Timing That Matches Your Benefit Dates
The best repayment schedule lines up with your actual deposit date. An app that tries to pull money before your benefits arrive can trigger overdraft fees at your bank.
4. Accessibility and Ease of Use
For many users, a clean, readable interface matters. Look for apps with clear text, simple steps, and responsive customer support through chat, email, or phone. Check whether the app works well with screen readers and other assistive tools if that applies to you.
5. Speed of Funding
Standard transfers can take a day or more. Instant transfers are faster, but may come with a fee. Know which option you are choosing before you confirm.
6. Reputation and Security
Look for bank-grade encryption, a clear privacy policy, and a track record of real user reviews. Be cautious with any service that asks for upfront payment, your full Social Security number without explanation, or access to anything beyond what is needed.
Read: Beem Instant Cash Advance During a War
Best Cash Advance Apps for Disability Recipients in 2026
Below is a balanced look at the options people on benefits most often consider. Always verify current limits, fees, and eligibility inside each app, since these change.
1. Beem
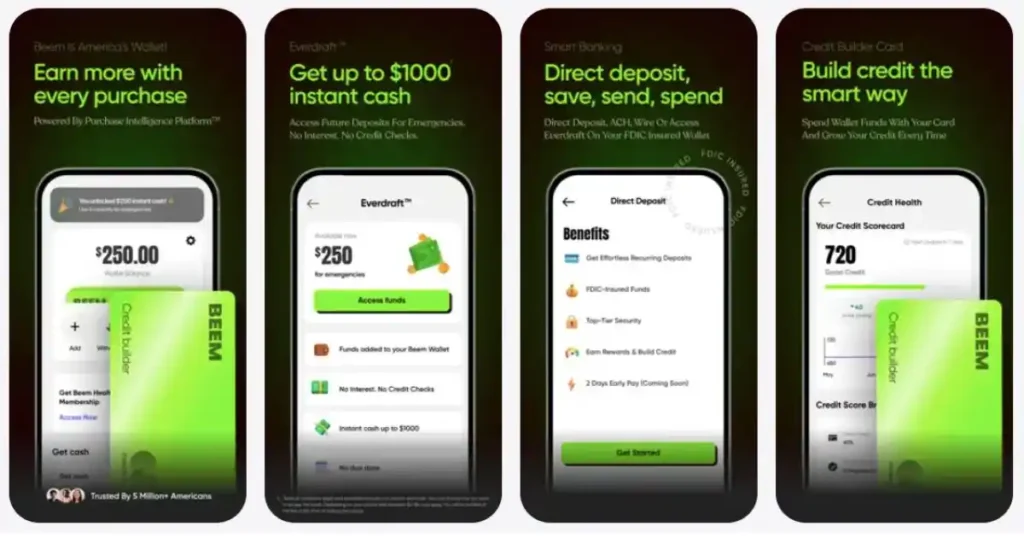
Beem is a financial technology app built around early access to your own upcoming deposits through a feature called Everdraft™. Eligible members can access from $10 up to $1,000, depending on plan and account activity.
Why It Stands Out for Disability Recipients
- It is not a loan. There is no interest, no credit check, and no fixed due date.
- There are no mandatory tips.
- Eligibility is based on account activity, which can be helpful if your income comes from benefits rather than a traditional paycheck.
- Beem’s own materials note that it serves people on government benefits, gig workers, and hourly earners.
Costs to Know About
Everdraft comes with a Beem subscription plan, with plans starting from $1.99 per month. Depending on how you choose to receive funds, a fee of up to $4 may apply. How much you can access depends on your account activity and can change over time.
Extras Worth Noting
Beem also bundles budgeting tools, cashback on gift cards, a personal loan marketplace for larger needs, and optional protection products such as job loss and disability coverage on premium plans.
2. Dave
Dave is a well-known app that offers small advances and budgeting features. It typically charges a monthly membership and may add an express fee for instant delivery.
Best For
People who want a simple app with budgeting alerts and who only need a small amount to cover a short gap.
Watch Out For
Advance limits start low for most new users, and fees for faster delivery can add up if you borrow regularly.
3. EarnIn
EarnIn is built around accessing wages you have earned. It can work for people with some earned income, though recurring benefit deposits may be treated differently depending on your account setup.
Best For
Users who combine benefits with part-time work and want an app that does not charge a mandatory fee.
Watch Out For
The model relies on optional tips and transfer fees, and approval can depend on proof of work-related income or regular deposit patterns.
4. Brigit
Brigit offers small advances alongside overdraft-style protection and budgeting tools, usually through a paid membership.
Best For
People who want predictive alerts when their balance is about to run low.
Watch Out For
The monthly subscription is a recurring cost even in months when you do not borrow.
5. MoneyLion
MoneyLion combines banking, credit-building tools, and small advances in one platform.
Best For
Users who want a full banking relationship and the chance to build credit at the same time.
Watch Out For
Some of the more valuable features require a paid membership or direct deposit into a MoneyLion account.
6. Chime SpotMe
Chime’s SpotMe feature lets eligible account holders overdraw their debit card up to a limit without an overdraft fee. It is not a standalone app. You need a Chime account.
Best For
People who are open to switching banks and whose benefits can be deposited directly into a Chime account.
Watch Out For
Limits are based on your direct deposit history, and new accounts typically start with a low limit.
7. Cleo
Cleo uses a chat-style interface for budgeting and small advances.
Best For
Users who like a conversational, easy-to-read experience.
Watch Out For
Advance size is generally modest, and some features sit behind a subscription.
A Word About “Cash Advance” Lead-Generation Sites
When you search for cash advance help, you will often find websites that look like lenders but are actually lead-generation platforms. Names like MoneyMutual, CashUSA, and similar services typically collect your details and pass them to a network of lenders.
These sites are not cash advance apps in the same sense. They can result in offers from lenders with high interest rates and short repayment windows. If you use one, read every term carefully, never agree to a loan you do not fully understand, and compare the total repayment cost against simpler options first.
How to Use a Cash Advance Responsibly on a Fixed Income
An advance is a tool, not a solution to a monthly shortfall. Used carefully, it can help you avoid a late fee or a shutoff notice. Used repeatedly, it can leave you short again the next month.
Borrow Only What You Truly Need
Pick the smallest amount that solves the immediate problem. A smaller advance means a smaller repayment hit on your next benefit deposit.
Time Your Advance Around Your Deposit Date
If your payment arrives in a few days, a short advance makes sense. If it is two weeks away, consider whether another option, such as calling a utility to request an extension, might cost less.
Track the Total Cost
Write down every fee, subscription charge, and tip before you accept an advance. If the total feels high relative to the amount, look elsewhere.
Avoid Stacking Multiple Apps
Using several apps at once can create overlapping repayments, all pulling from the same deposit. That is the fastest way to end up overdrawn.
Build a Small Buffer
Even $25 to $50 set aside each month can reduce your need for advances over time. Many apps and banks now offer automatic round-up savings that make this easier.
Alternatives to Cash Advance Apps for People on Disability
An app is not always the best answer. Depending on your situation, one of these may cost less or provide more support.
Emergency Assistance Programs
- Local community action agencies can sometimes help with rent, utilities, and food.
- Dialing 211 connects you to local services, including emergency financial assistance.
- Nonprofits and faith-based organizations often run one-time assistance funds.
- State and county benefit offices may offer emergency programs for eligible residents.
Credit Union Small-Dollar Loans
Many credit unions offer small, low-interest loans designed as alternatives to payday lending. Membership requirements are often flexible, and rates are usually far lower than those of non-bank lenders.
Payment Plans and Hardship Requests
Utility companies, landlords, medical providers, and pharmacies frequently have hardship or payment plan options. A short phone call can sometimes remove the need to borrow at all.
Personal Loan Marketplaces
For larger needs, comparing offers through a loan marketplace can help you see rates and terms side by side before you commit. Beem’s marketplace, for example, lets users compare offers from lending partners, with rates and terms shown upfront and varying by lender and eligibility.
SSA Resources
If you are waiting on an initial benefit payment or have a payment problem, contact the Social Security Administration directly. In some circumstances, the SSA offers ways to address delays or emergencies. A local SSA office or its official phone line can explain what applies to you.
Red Flags to Avoid
People on fixed incomes are sometimes targeted by scams and predatory lenders. Walk away if you see any of the following:
- A request for an upfront “processing” or “insurance” fee before you receive funds
- Guaranteed approval with no review of any kind
- Pressure to act immediately or to keep the transaction secret
- Requests for your SSA login, online banking password, or full card PIN
- Terms that are not clearly shown before you sign
- Repayment tied to access to your benefit account in ways you do not understand
If something feels off, trust that instinct and look for an alternative.
Step-by-Step: How to Apply for a Cash Advance Using Your Disability Income
The process is similar across most apps.
Step 1: Check Your Bank Account Setup
Make sure your benefits are deposited into a checking account that is in good standing. Direct deposit history is often the most important factor in approval.
Step 2: Compare Two or Three Apps
Read the fee pages, not just the marketing. Look at monthly costs, express transfer fees, and any optional tips.
Step 3: Download and Create an Account
Provide your basic information and link your bank account. Most apps use a secure connection to read your transaction history.
Step 4: Review Your Offer
The app will show how much you can access and what it will cost. Read the repayment date and the total fees before you confirm.
Step 5: Receive and Repay
Choose your delivery speed, receive your funds, and make sure your account has enough to cover repayment on the scheduled date. Setting a calendar reminder for a day or two before is a smart habit.
Final Thoughts
Cash advance apps can be a helpful safety net when you live on a fixed disability income and a bill lands at the wrong time. The key is choosing an app with clear pricing, repayment that fits your benefit schedule, and terms you can understand at a glance.
Compare your options, borrow only what you need, and use local assistance programs and credit unions where they make sense. If you want an option built around early access to your own deposits, with no interest and no credit check, Beem’s Everdraft is worth a look alongside the other apps in this guide.
Check out Beem for on-point financial insights and recommendations to spend, save, plan and protect your money like an expert. Download the Beem app today!
Frequently Asked Questions
1. Can I get a cash advance if my only income is SSI or SSDI?
Often, yes. Many cash advance apps evaluate your bank account activity and recurring deposits rather than the type of employer paying you. If your SSI or SSDI arrives regularly in a checking account, some apps may treat it as qualifying income. Approval and advance amounts vary by app, and no provider can guarantee approval.
2. Will a cash advance affect my disability benefits?
It depends on your benefit type and personal situation. Money you are required to repay is generally treated differently from income, but SSI has detailed resource and income rules. Because the stakes are higher for means-tested benefits, check with the SSA or a benefits counselor if you plan to borrow often or hold larger balances.
3. Are there cash advance apps with no credit check for people on disability?
Yes. Several apps, including Beem, do not require a hard credit check. Instead, they review factors such as your deposit history and account activity. Always read the terms to confirm how repayment is handled and whether any missed payment could be reported.
4. What is the cheapest way to get a small advance on a fixed income?
The lowest-cost options are usually a payment plan or extension from the biller, a local assistance program, or a credit union small-dollar loan. If you choose an app, compare subscription fees, instant transfer charges, and tips. An app with a flat, transparent cost and no required tips will usually be cheaper than one that relies on optional extras.
5. How can I avoid getting stuck in a cycle of borrowing?
Borrow only what you need, avoid using several apps at once, and make sure the repayment date falls after your benefit deposit. Over time, try to build a small emergency buffer, even if it is only a few dollars a month. If you find yourself needing an advance every month, a free session with a nonprofit credit counselor can help you rework your budget.