Table of Contents
Car insurance is one of those expenses that can quietly take a bigger bite out of your monthly budget than expected. If you’re driving in Kansas, you need enough coverage to stay legal and financially protected, but that doesn’t mean you have to settle for the first quote you receive.
The good news is that cheap car insurance in Kansas is available, but the cheapest company for one driver may be completely different for another. Your age, driving history, ZIP code, vehicle, credit history, coverage limits, and even how much you drive can all affect your premium.
Recent 2026 data shows just how much rates can vary. Experian puts the average Kansas car insurance cost at about $1,756 per year, or $146 per month, with average minimum coverage at $1,344 annually and full coverage at $2,509. Other rate studies produce different averages because they use different driver profiles and methodologies.
So, where should you start if you’re looking for affordable auto insurance in Kansas? This guide explains Kansas car insurance requirements, average rates, the cheapest coverage options, factors that affect your premium, discounts to look for, and practical ways to lower your insurance costs without leaving yourself dangerously underinsured.
What Is the Cheapest Car Insurance in Kansas?
There isn’t one insurance company that is guaranteed to be the cheapest for every Kansas driver. Current 2026 rate comparisons show different insurers leading depending on the coverage level and driver profile.
For example, Experian has June 2026 data that found Root had the lowest average quoted price for both minimum coverage and full coverage among the carriers it analyzed. Its average minimum-coverage quote was about $808 per year, while its average full-coverage quote was about $1,503 per year.
NerdWallet has an August 2026 analysis that produced a different result, finding GEICO had the cheapest average minimum coverage at about $401 per year, and Travelers had the cheapest average full coverage at about $1,485 per year.
These differences illustrate an important point: rate comparisons are useful starting points, not guarantees of what you’ll personally pay.
| Coverage | Example low-cost option in 2026 | Approx. annual rate |
| Minimum coverage | GEICO | $401 |
| Minimum coverage | Root | $808 |
| Full coverage | Travelers | $1,485 |
| Full coverage | Root | $1,503 |
The figures above come from different insurers’ 2026 rate studies, so they aren’t directly comparable as quotes for the same driver profile. Your actual premium may be significantly different.
How Much Does Car Insurance Cost in Kansas?
The average Kansas car insurance premium varies depending on the source and the type of policy being measured. Experian’s June 2026 data puts the overall average at approximately:
- $1,756 per year
- $146 per month
- $1,344 per year for minimum coverage
- $2,509 per year for full coverage
NerdWallet’s August 2026 analysis found an average of approximately $612 per year for minimum coverage and $2,502 per year for full coverage. Why the difference?
Insurance studies don’t all use the same drivers, vehicles, coverage limits, geographic areas, or methodology. That’s why an “average Kansas rate” should be viewed as a benchmark rather than a price you should expect to receive.
What Is the Minimum Car Insurance Required in Kansas?
Kansas requires drivers to maintain certain minimum insurance coverage. The state’s minimum requirements include:
- $25,000 per person for bodily injury liability.
- $50,000 per accident for bodily injury liability.
- $25,000 per accident for property damage liability.
- $25,000 per person / $50,000 per accident for uninsured and underinsured motorist bodily injury coverage.
- Personal Injury Protection (PIP) coverage.
Kansas is also a no-fault state, which means PIP coverage plays an important role in paying certain medical and related expenses after an accident, regardless of who caused the crash.
Meeting these requirements keeps you legally insured, but minimum coverage isn’t necessarily the best financial protection for every driver.
What Does Kansas PIP Insurance Cover?
Personal Injury Protection is required in Kansas and is designed to help cover certain losses resulting from injuries sustained in an automobile accident.
Kansas requires PIP benefits that include:
- Up to $4,500 per person for medical expenses.
- Up to $900 per month for disability or loss of income for one year.
- Up to $25 per day for in-home services.
- Up to $2,000 for funeral, burial, or cremation expenses.
- Up to $4,500 for rehabilitation expenses.
- Certain survivor benefits.
Because Kansas is a no-fault state, PIP can provide important protection even when another driver is responsible for the accident.
What Is Liability Insurance?
Liability insurance pays for certain injuries or property damage you cause to other people when you’re legally responsible for an accident. It generally includes two major components.
Bodily Injury Liability
This helps cover injuries to other people when you are responsible for an accident, subject to your policy limits.
Property Damage Liability
This helps pay for damage you cause to another person’s vehicle or property.
Kansas requires both types of liability coverage.
The minimum limits are relatively modest compared with the potential cost of a serious accident, which is why many drivers choose higher limits.
What Is Uninsured and Underinsured Motorist Coverage?
Uninsured motorist coverage helps protect you if you’re injured in an accident caused by a driver who doesn’t have the required insurance.
Underinsured motorist coverage can help when the at-fault driver’s insurance isn’t enough to cover the damages.
Kansas requires uninsured and underinsured motorist bodily injury coverage at minimum limits of $25,000 per person and $50,000 per accident.
This coverage can be particularly valuable because an accident can create medical expenses and other losses that exceed the at-fault driver’s available insurance.
What Is Full Coverage Car Insurance in Kansas?
“Full coverage” isn’t a specific insurance policy required by Kansas law. The term generally refers to a policy that combines liability coverage with collision and comprehensive coverage.
Collision Coverage
Collision coverage can help pay to repair or replace your vehicle after a covered collision, subject to your deductible and policy limits.
Comprehensive Coverage
Comprehensive coverage protects against many types of non-collision damage, such as:
- Theft.
- Vandalism.
- Fire.
- Hail.
- Falling objects.
- Certain weather-related damage.
- Animal-related damage.
Kansas drivers aren’t legally required to carry comprehensive or collision coverage on a fully owned vehicle. However, a lender or leasing company will often require it if you’re financing or leasing your car.
Is Minimum Coverage the Cheapest Option?
Usually, yes. Buying only the coverage required by Kansas law will generally cost less than purchasing a policy with higher liability limits and comprehensive and collision coverage. But “cheapest” doesn’t always mean “best value.”
Imagine you’re involved in a serious accident, and your liability limits aren’t enough to cover the other driver’s damages. You could potentially become personally responsible for amounts beyond your policy limits.
That’s why it’s worth considering your assets, income, vehicle value, and financial risk before choosing minimum coverage solely because it has the lowest premium.
Cheapest Minimum Coverage Car Insurance in Kansas
If your primary goal is the lowest possible premium while remaining legally insured, minimum coverage is generally the place to start. NerdWallet’s August 2026 analysis found these insurers among the lowest-priced options for minimum coverage for its benchmark driver:
- GEICO.
- Travelers.
- Shelter.
- State Farm.
- Farm Bureau Financial Services.
The actual ranking can change depending on your age, location, driving record, credit history, and other factors.
Cheapest Full Coverage Car Insurance in Kansas
Full coverage costs more because you’re buying protection for your own vehicle in addition to liability coverage.
NerdWallet’s August 2026 analysis identified Travelers as its cheapest full-coverage option for a benchmark Kansas driver, with an average rate of approximately $1,485 per year.
Experian’s June 2026 data instead found Root at approximately $1,503 per year, followed by Liberty Mutual Direct, National General, GEICO, and Progressive. Again, these are averages based on specific quote data rather than guaranteed prices.
Cheapest Car Insurance for Young Drivers in Kansas
Young drivers typically pay more for car insurance because insurers generally consider inexperienced drivers to represent a higher risk. If you’re in your late teens or early twenties, getting multiple quotes can make a substantial difference.
NerdWallet’s 2026 analysis found Travelers, Progressive, and GEICO among the more affordable options for young Kansas drivers, although the cheapest company varied depending on the driving record. Young drivers can also look for:
- Good student discounts.
- Defensive driving discounts.
- Safe-driving programs.
- Multi-policy discounts.
- Family policy discounts.
Staying on a parent’s policy, when appropriate and permitted by the insurer, can also sometimes be less expensive than purchasing an entirely separate policy.
Cheap Car Insurance for Drivers With a Speeding Ticket
A speeding ticket can increase your insurance premium because insurers may view it as evidence of higher driving risk. However, the increase isn’t identical across insurance companies.
NerdWallet’s Kansas analysis found Travelers among the lower-cost options for drivers with a recent speeding ticket, followed by companies including Progressive and GEICO.
If you’ve recently received a ticket, don’t assume your current insurer is still your cheapest option. Get new quotes after the violation is added to your driving record.
Cheap Car Insurance After an Accident
An at-fault accident can cause your premium to increase, sometimes significantly. The best way to find affordable coverage after an accident is to compare insurers rather than assuming your current provider is the cheapest.
NerdWallet’s 2026 Kansas analysis found Travelers among its lowest-cost options for drivers with an accident, with Progressive and GEICO also appearing among the more affordable choices.
Your premium can depend on:
- Whether you were at fault.
- The severity of the accident.
- The cost of the claim.
- Your previous driving record.
- Your insurer’s accident-forgiveness policies.
Cheap Car Insurance After a DUI in Kansas
A DUI can have a substantial effect on car insurance premiums. Drivers with a DUI are generally considered higher risk, so insurers may charge significantly more.
NerdWallet’s August 2026 analysis found Travelers among the lower-cost options for Kansas drivers with a DUI, followed by Progressive and other insurers depending on the driver profile.
If you have a DUI on your record, compare several insurers rather than accepting the first quote available. You may also need to satisfy additional state requirements depending on your circumstances.
Cheap Car Insurance for Drivers With Poor Credit
Credit history can influence car insurance pricing in many states, although insurers and state regulations differ.
If your credit history is hurting your insurance rate, shopping around becomes particularly important because companies can weigh credit-related factors differently.
NerdWallet’s 2026 Kansas analysis found Travelers among the lower-cost options for drivers with poor credit, although individual rates can vary substantially. Improving your credit over time can potentially help reduce insurance costs, but you should still compare quotes rather than waiting for your credit to improve before shopping around.
Check this out: Save up to 40% on car insurance
Does Your ZIP Code Affect Kansas Car Insurance Rates?
Yes. Where you live can influence your premium because insurers consider factors such as:
- Accident frequency.
- Theft rates.
- Population density.
- Repair costs.
- Weather risks.
- Claims history.
- Traffic patterns.
Current Kansas rate data shows meaningful differences between cities. For example, Experian’s 2026 data lists average monthly premiums around $195 in Wichita, $171 in Kansas City, $170 in Overland Park, $157 in Topeka, and $146 in Lawrence.
You generally can’t change your ZIP code simply to get cheaper insurance, but knowing that location matters can help explain why two Kansas drivers with similar vehicles and driving records receive different quotes.
How Does Your Car Affect Insurance Cost?
The vehicle you drive can have a major impact on your premium. Insurers may consider:
- Vehicle value.
- Repair costs.
- Theft rates.
- Safety features.
- Crash-test performance.
- Engine power.
- Replacement-part costs.
- Historical claims for the model.
A newer luxury vehicle may cost substantially more to insure than an older economy car. If you’re shopping for a vehicle and want to keep ownership costs low, get insurance quotes for the models you’re considering before buying.
Does Driving Less Lower Car Insurance?
It can. Some insurers consider annual mileage when calculating premiums. If you drive relatively few miles each year, ask insurers whether they offer:
- Low-mileage discounts.
- Usage-based insurance.
- Pay-per-mile programs.
Usage-based insurance programs may also consider driving behaviors such as braking, acceleration, speed, and time of day. If you’re comfortable sharing driving data with your insurer, such a program may be worth exploring.
How Can I Get Cheap Car Insurance in Kansas?
Finding affordable coverage generally comes down to comparing quotes and managing the factors you can control. Here are some of the most effective strategies.
Compare Multiple Insurance Companies
Don’t assume that the company advertising the lowest rates will actually offer you the lowest price. Get quotes from several insurers using the same coverage limits and deductibles. Otherwise, you’re comparing different policies rather than different prices for equivalent coverage.
Ask About Discounts
Insurance companies offer different discounts, and not all are automatically applied. Ask whether you qualify for:
- Safe-driver discounts.
- Multi-car discounts.
- Bundling discounts.
- Good-student discounts.
- Defensive-driving discounts.
- Anti-theft discounts.
- Low-mileage discounts.
- Automatic-payment discounts.
- Paid-in-full discounts.
A few discounts combined can make a meaningful difference.
Raise Your Deductible
If you have comprehensive and collision coverage, increasing your deductible can lower your premium. For example, moving from a $500 deductible to a $1,000 deductible may reduce your monthly cost.
But only choose a deductible you can comfortably afford if you need to file a claim. A lower premium isn’t useful if you can’t cover the deductible after an accident.
Bundle Your Insurance
If you have homeowners, renters, or other insurance, ask whether bundling your policies with one insurer would reduce your overall cost.
The discount may not always make the bundled policy cheapest, so compare the total price rather than assuming bundling is automatically better.
Maintain a Clean Driving Record
Your driving history is one of the factors insurers can use when pricing your policy.
Avoiding:
- Speeding tickets.
- Reckless driving.
- At-fault accidents.
- DUI offenses.
can help keep your insurance costs under control over time.
Improve Your Credit Where It Matters
If your insurer considers credit-based insurance factors, improving your credit profile may eventually help your premium. Focus on fundamentals such as:
- Paying bills on time.
- Reducing revolving debt.
- Avoiding unnecessary new credit applications.
- Checking your credit reports for errors.
Insurance pricing doesn’t change instantly when your credit improves, so continue comparing quotes.
Choose the Right Coverage
One of the easiest ways to reduce your insurance bill is to avoid paying for coverage you don’t need. But that doesn’t mean automatically choosing the legal minimum. Instead, consider your financial situation.
If you have an older vehicle worth relatively little, carrying comprehensive and collision coverage may not make economic sense after considering premiums and deductibles.
If you have a newer vehicle or a financed car, dropping those coverages may be unrealistic or financially risky.
Minimum Coverage vs. Full Coverage in Kansas
| Feature | Minimum Coverage | Full Coverage |
| Meets Kansas legal requirements | Yes | Yes |
| Bodily injury liability | Yes | Yes |
| Property damage liability | Yes | Yes |
| PIP | Yes | Yes |
| Uninsured/underinsured motorist | Yes | Yes |
| Collision coverage | No | Usually |
| Comprehensive coverage | No | Usually |
| Protects your own vehicle | Limited | More extensive |
| Typical premium | Lower | Higher |
If your vehicle is financed or leased, your lender will generally require comprehensive and collision coverage. If you own the vehicle outright, you have more flexibility.
What Should You Ask an Insurance Company Before Buying?
Before accepting a cheap quote, ask:
- What are the liability limits?
- What is the deductible?
- Does the policy include comprehensive and collision coverage?
- What PIP benefits are included?
- What uninsured and underinsured motorist coverage is included?
- Are there policy exclusions?
- Are there discounts I haven’t received?
- How does the insurer handle claims?
- Is the quote based on the correct mileage and vehicle information?
A low premium is only meaningful if you understand what you’re buying.
How Beem Can Help You Manage Car Insurance Costs
Car insurance is a recurring expense, so it belongs in your regular monthly budget rather than being treated as an occasional bill.
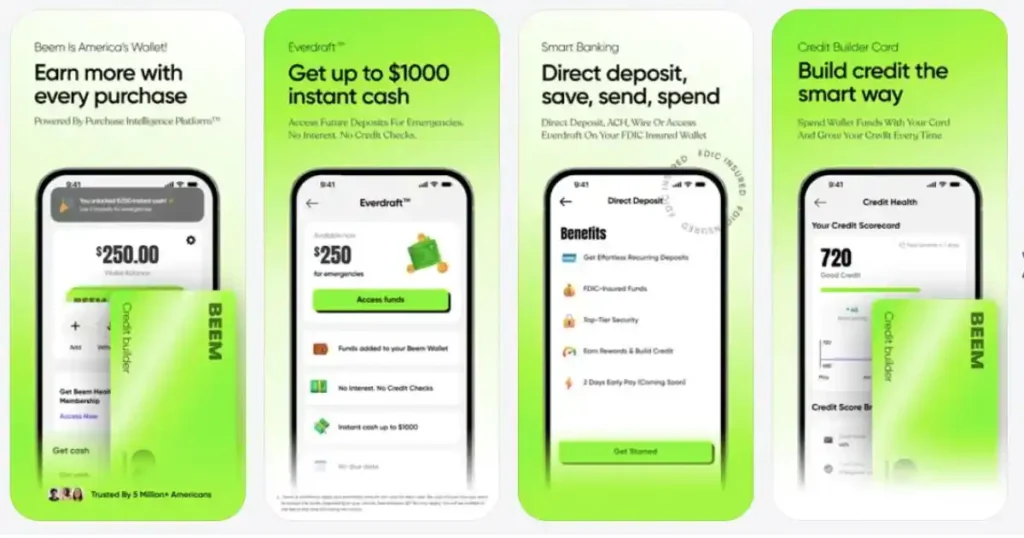
Beem can help you track recurring expenses, monitor spending, organize your budget, and get a clearer picture of your cash flow. That can make it easier to plan for insurance premiums alongside rent, utilities, groceries, fuel, and other household expenses. Beem’s marketplace also helps you choose the best car insurance premium.
For eligible users facing a temporary cash shortage, Beem Everdraft™ may also provide access to up to $1,000 in instant cash advances, subject to applicable eligibility requirements. This can provide additional flexibility when an unexpected car-related expense or other bill arrives before your next paycheck.
Conclusion
Finding cheap car insurance in Kansas isn’t necessarily about finding one insurer with the lowest advertised rate. It’s about finding the lowest price for the coverage that actually fits your circumstances.
Kansas requires liability insurance, PIP, and uninsured/underinsured motorist coverage, but drivers can choose additional protection such as comprehensive and collision coverage. Current 2026 rate studies show substantial differences between insurers, which is why comparing multiple quotes can make a meaningful difference.
Before choosing a policy, compare the same coverage limits across several insurers, ask about discounts, consider your deductible carefully, and review your policy each year.
Most importantly, don’t sacrifice important protection simply to save a few dollars each month. The cheapest policy is only a good deal if it leaves you adequately protected when you actually need it.
Frequently Asked Questions
1. What is the cheapest car insurance in Kansas?
There isn’t one company that is cheapest for every Kansas driver. In 2026, different rate studies identify different insurers as the lowest-cost options. GEICO, Travelers, Root, and others appear among the cheapest depending on coverage level and driver profile. Your actual quote can vary significantly based on your circumstances.
2. How much is car insurance in Kansas per month?
Average rates vary by coverage and methodology. Data puts the overall Kansas average at about $146 per month, while minimum coverage averages about $112 and full coverage about $209. Individual quotes can be much lower or higher.
3. What is the minimum car insurance required in Kansas?
Kansas requires $25,000 per person and $50,000 per accident in bodily injury liability, $25,000 in property damage liability, 50,000 in uninsured and underinsured motorist bodily injury coverage, and required PIP benefits.
4. Is Kansas a no-fault car insurance state?
Yes. Kansas is a no-fault state, which is why drivers are required to carry personal injury protection. PIP can help pay certain medical and other covered expenses after an accident regardless of who caused it.
5. What is the cheapest full coverage car insurance in Kansas?
The answer depends on the driver profile and source. NerdWallet’s August 2026 analysis found Travelers had the lowest average full-coverage rate among the companies it analyzed, while Experian’s June 2026 data found Root had the lowest average quote.